Inflation interrupts the rebound
U.S. stocks fell on October 14, led by technology. The Bureau of Labor Statistics released September CPI at 8:30 a.m. Eastern Time: prices rose 3.7% year over year and 0.6% month over month. Renewed inflation pressure put rate increases back in focus. AP reported rising Treasury yields and selling in AI stocks. The prospect of higher financing costs offers the clearest explanation for pressure on technology valuations built around strong growth expectations.
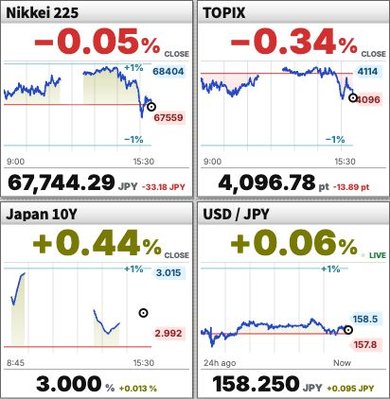
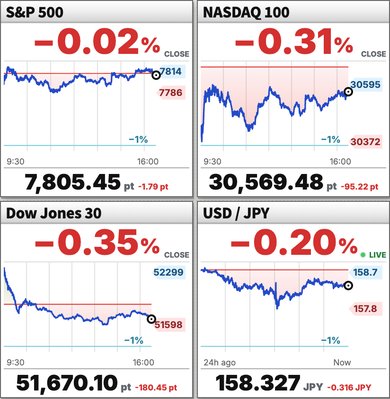
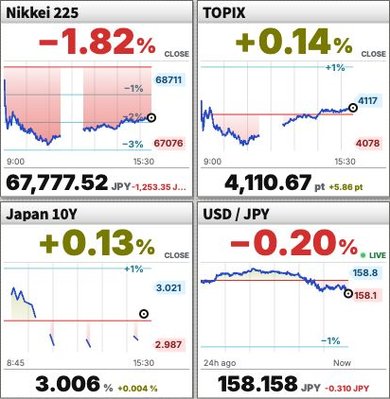
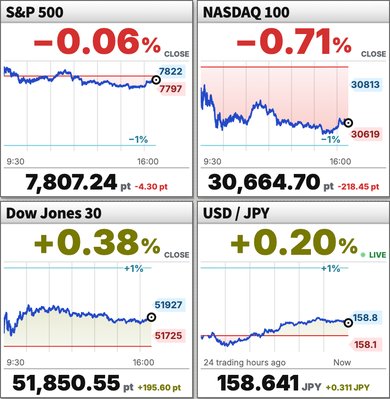
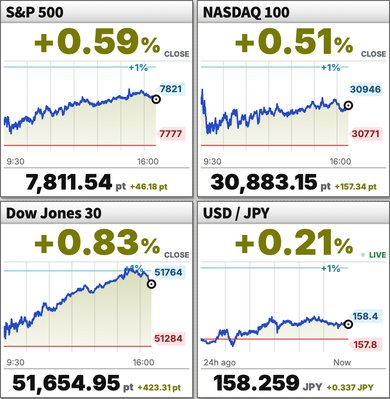
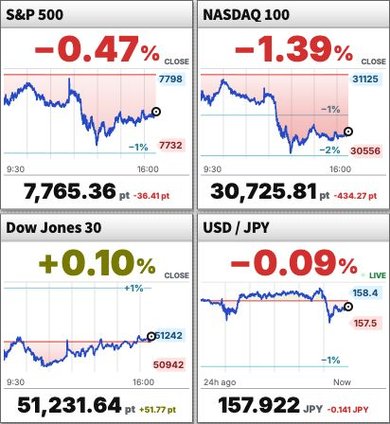
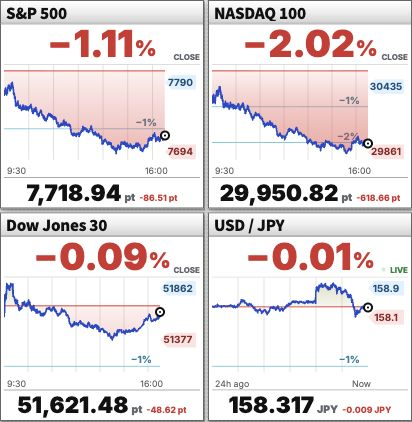
The S&P 500 and Nasdaq 100 charts show their early rebounds fading, followed by progressively lower lows. The decline from morning into afternoon exceeded roughly 0.5%. CPI arrived before the opening bell, rather than at the same moment as a sharp intraday fall. A continuing reassessment of interest rates after the inflation release best explains why rebounds repeatedly failed to attract lasting buying.
The Dow recovers without lifting the whole market
The Dow also reversed an early rise, but recovered more substantially from its afternoon low and limited its closing decline. The Nasdaq 100’s late rebound was modest, and the S&P 500 remained well below its previous close. Buying into the finish was insufficient to absorb the selling concentrated in technology. The gap between the indexes points to greater caution toward growth stocks sensitive to rising rates.
On the rolling 24-hour chart, USD/JPY rose and then reversed, failing to hold its high. Dollar buying associated with higher yields did not persist in one direction. Its time axis differs from the stock charts, so no precise reversal time is assigned. Neither equities nor currencies simply carried their initial reaction through to the end of the session.
Closing levels: AP’s final table and Nasdaq.
Major Index Closes
- S&P 5007,718.94 −1.11%
- NASDAQ 10029,950.82 −2.02%
- Dow Jones 3051,621.48 −0.09%