A record close without an uninterrupted advance
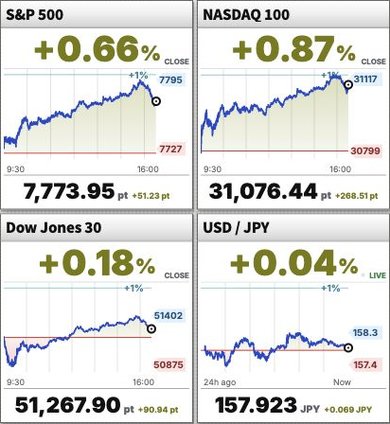
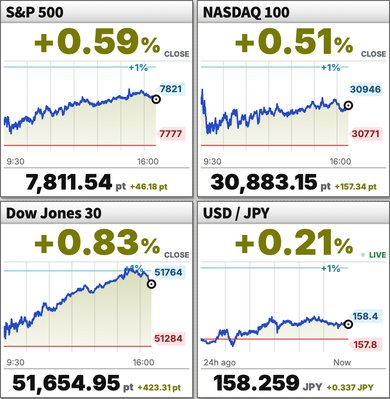
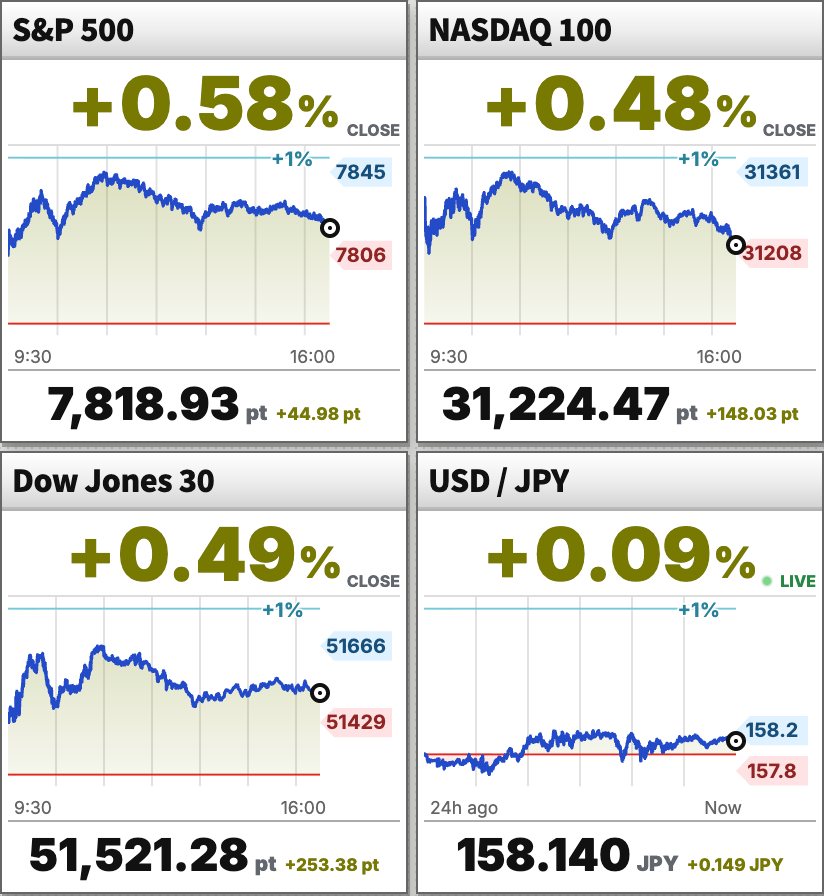
All three major indexes covered here rose on October 6. Final S&P 500 and Dow levels come from AP’s closing table, while the Nasdaq 100 figure comes from Nasdaq’s official index page. The S&P 500 set a record, but the chart shows prices retreating from their morning highs. A positive daily close does not necessarily mean buying strengthened throughout the session. This was a day when the market retained part of the gains established early on.
AP’s market report identifies earnings expectations and easing yields as support. The 10-year Treasury yield fell to 5.28% from 5.31%. Stronger profit expectations and a modest reduction in discount-rate pressure made early buying more attractive. Yields had not returned to a low-rate environment, however, so a favorable backdrop did not guarantee sustained buying at the highs.
Strong morning recoveries, less durable afternoon rebounds
Equity times below are approximate and in U.S. Eastern Time. The S&P 500 and Nasdaq 100 rose after the open, pulled back around 10:30 a.m., then attracted renewed buying. Recovering from that dip to challenge higher levels shows that morning demand extended beyond the initial advance. The Dow displays a similar pullback and recovery, making this more than a one-way rally confined to technology shares. As yield concerns eased somewhat, buying extended across several indexes.
Charles Schwab’s 9:11 a.m. update reported an oil decline of about 2%, alongside lower yields, as a favorable premarket backdrop. It also identified Constellation Energy’s electricity-supply agreement with Google as a catalyst for early individual-stock buying. Cheaper oil eases concerns over company costs and inflation, while the power agreement supports expectations that AI-related investment will generate revenue. Together, these provide a concrete explanation for the morning recovery.
The pattern subsequently changed. After elevated levels around 11:30 a.m.–noon, the S&P 500 and Nasdaq 100 gave back ground until roughly 1:30 p.m. A recovery around 2 p.m. failed to reclaim the morning highs. The Nasdaq 100 weakened again into the close, and the S&P 500 also slipped late. Profit-taking after the advance appears to have outweighed fresh afternoon demand, which best fits the failure of those rebounds to persist.
The Dow steadied during the afternoon and finished after smaller fluctuations. Closing percentage gains across the three indexes were similar, and all remained positive despite their retreat from the morning highs. The central pattern was a partial reversal of an early advance rather than a collapse of the day’s upward bias. The record-close headline should be read alongside the afternoon’s inability to recover the morning peak.
Reading the sharper moves and USD/JPY
The morning recovery from the dip shows a move of roughly 0.5% in the S&P 500 and Nasdaq 100. Confirmed reporting points to easing yields and earnings expectations as support, placing the rebound within that broader buying backdrop. It is best interpreted as favorable factors regaining influence after early selling, rather than labeling it an immediate reaction to a particular economic release. During the afternoon, those same factors were insufficient to hold the highs, and the market became less able to absorb selling after the advance.
The 24-hour USD/JPY chart weakens on its left side, recovers around the middle and includes smaller dips later. Its horizontal axis differs from the cash-equity session, so its trough should not be assigned the same time as the morning stock-market pullback. The image mainly shows movement within a narrow range rather than a one-way shock of roughly 0.5%. Lower yields, which supported stocks, would generally restrain the dollar, but the currency did not follow a steady downward path. Reading equity earnings and yields separately from the currency’s 24-hour swings avoids attributing the morning stock rally entirely to yen weakness.
Major Index Closes
- S&P 5007,818.93 +0.58%
- NASDAQ 10031,224.47 +0.48%
- Dow Jones 3051,521.28 +0.49%