Growth shares overcome the drag from high yields
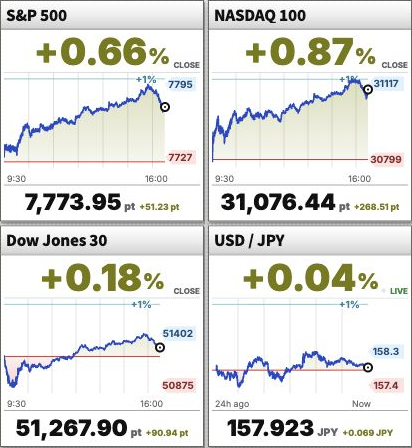
U.S. stocks extended their gains on October 5. The Associated Press closing table put the S&P 500 at 7,773.95, up 51.23 points or 0.66%, and the Dow at 51,267.90, up 90.94 points or 0.18%. Nasdaq reported a Nasdaq 100 close of 31,076.44, up 0.87%. Its roughly 0.69-percentage-point lead over the Dow identifies growth shares as the stronger part of the market.
The AP market report highlighted a surge in PTC following Schneider’s announced acquisition. Meanwhile, the U.S. 10-year Treasury yield rose to 5.31% from 5.28% in the previous session. This was not an advance driven by falling yields. Company-specific valuation support outweighed the pressure from high discount rates. A software acquisition provides a concrete signal that a buyer sees value in a business and its customer base. Selective demand for growth businesses with earnings power, rather than blanket optimism about the economy, best explains the leadership.
An early dip gives way to a sustained recovery
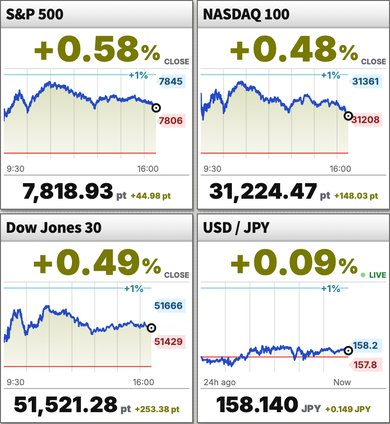
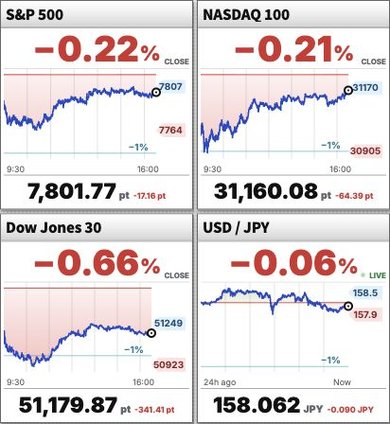
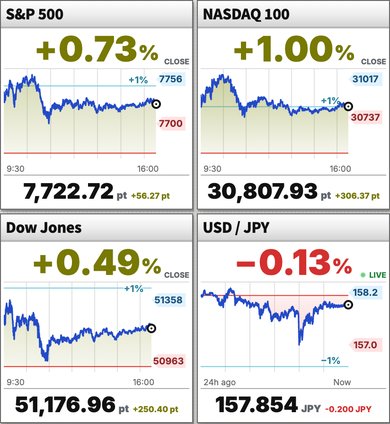
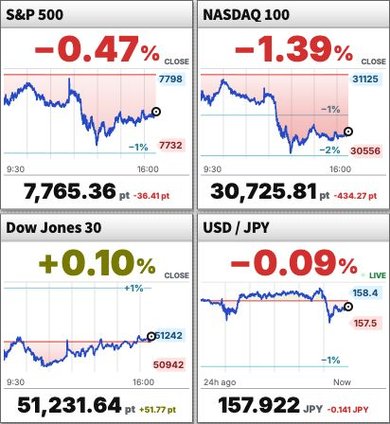
The site’s charts show the S&P 500 and Nasdaq 100 absorbing weakness around the open before climbing through the morning and afternoon. The Dow falls sharply just after the 9:30 a.m. Eastern opening and rebounds during roughly the first hour. That downswing and recovery span about 0.5% or more. Buyers absorbed the initial selling, and the indexes subsequently stayed clear of the lower opening range. The key signal is not the first move, but the level that held after it.
The ISM Services report, released at 10 a.m., showed a headline reading of 54.9 versus 55.4 in August, still above the 50 expansion threshold. Its prices index rose to 74.0. Continued growth and persistent cost pressure are the important combination. The release was a major scheduled event near the early recovery: it points to demand holding up while inflation concerns remain. Deal-driven revaluation and continuing service-sector expansion supported buying, while rising price pressure restrained expectations for a broad decline in yields.
Late profit-taking trims the advance without erasing it
The two more growth-oriented indexes reached fresh intraday highs in the afternoon, then surrendered part of the advance near the close. The Dow also turned higher late but finished with a smaller gain. Side by side, the charts show persistent Nasdaq 100 leadership rather than uniform strength across the market. Late selling is best read as profit-taking meeting the valuation constraint imposed by high yields. Both the S&P 500 and Nasdaq 100 nevertheless finished above their early-session levels: the day’s buying left a meaningful gain behind.
USD/JPY’s 24-hour chart rises into the 158s and then retreats into the 157s. The displayed low-to-high range is about 0.5% or more, but its time window differs from the equity indexes’ regular session. Elevated U.S. yields support the dollar, while the round trip shows that high yields alone did not sustain the currency advance. Comparing relative index strength separately from the currency’s reversal gives a clearer account of the session than simply equating rising stocks with a stronger dollar. In the next session, watch whether the Nasdaq 100 can hold its afternoon range with yields still elevated, and whether that resilience extends more broadly to the S&P 500.
Major Index Closes
- S&P 5007,773.95 +0.66%
- NASDAQ 10031,076.44 +0.87%
- Dow Jones 3051,267.90 +0.18%